As a typical refractory metal product, tungsten filaments have maintained an irreplaceable position in global high-end manufacturing with their excellent high-temperature resistance, mechanical properties and electrical stability. Driven by the upgrading of downstream industries such as photovoltaics, semiconductors and aerospace, the tungsten filament industry is undergoing a new round of technological iteration and structural adjustment. This article will elaborate on the core knowledge, technological breakthroughs, application expansion and future trends of tungsten filaments, providing professional insights for practitioners in the refractory metal processing industry.
Basic Properties and Classification of Tungsten Filaments
Core Physical and Chemical Properties
Tungsten filaments are linear materials mainly composed of tungsten with a purity generally higher than 99.95%, prepared through powder metallurgy and high-temperature swaging processes. As a representative refractory metal material, tungsten filaments exhibit outstanding comprehensive properties: their melting point reaches 3410±20℃, significantly higher than most metal materials, making them the preferred conductor for extreme high-temperature environments. The density at room temperature is 19.25g/cm³, and the tensile strength of tungsten filaments with a diameter of 0.1mm can reach tens of gigapascals, with an elongation rate maintained at 3%-5%, combining high strength and appropriate ductility to withstand complex stress environments.
In terms of electrical properties, the resistivity of tungsten filaments is 5.6×10⁻⁸Ω·m. Although its conductivity is lower than that of silver and copper, it has excellent stability at high temperatures—the fluctuation range of resistivity is less than 5% when the temperature rises to 2000℃. In terms of thermal expansion, the linear expansion coefficient of tungsten filaments in the range of 20-1000℃ is 4.5×10⁻⁶/℃, which has excellent matching with the thermal expansion coefficient of glass materials, laying a solid foundation for their application in vacuum tube packaging.
Classification by Composition and Application
Tungsten filaments can be divided into multiple categories according to doping elements and application scenarios, each with unique performance characteristics:
Doped tungsten filaments, also known as non-sag tungsten filaments, are prepared by adding a small amount of potassium oxide, silicon oxide and aluminum oxide during the smelting process (the total dosage does not exceed 1%). This type of tungsten filament has excellent high-temperature anti-sagging performance and is widely used in incandescent lamps, halogen lamps and festival lights, with typical grades such as WB001 and WB150. Tungsten-rhenium filaments add 3%-5% rhenium to doped tungsten filaments, which can reduce the ductile-brittle transition temperature of tungsten to room temperature or below, significantly improving the toughness of the filament, and are suitable for high-reliability light source products and aerospace sensors.
Tungsten-thorium filaments and tungsten-cerium filaments are mainly used as electrodes for gas discharge lamps. Tungsten-thorium filaments contain 0.5%-3% thorium to reduce the electron work function, but due to thorium’s radioactivity, tungsten-cerium filaments are gradually replacing them in small-power devices. In addition, composite tungsten filaments such as tungsten-copper composite filaments integrate the high melting point of tungsten and the high conductivity of copper, and are widely used in aerospace and electronic systems that require both high temperature resistance and electrical performance.
Manufacturing Process and Technological Innovations
Traditional Production Process Flow
The traditional production of tungsten filaments mainly uses ammonium paratungstate (APT) as the raw material, going through multiple processes: first, APT is calcined in air at about 500℃ to form tungsten trioxide, or slightly reduced in hydrogen at 450℃ to form blue tungsten oxide. For doped tungsten filaments, doping agents such as potassium oxide are added at this stage. Then, the tungsten oxide is reduced in two steps—first to tungsten dioxide at about 630℃, and then to metal tungsten powder at 820℃—to ensure the full effect of doping elements and control powder particle size.
The obtained tungsten powder is pressed into slender square bars, which are sintered by self-resistance heating in hydrogen at about 3000℃, with the density reaching more than 85% of the theoretical value. The sintered tungsten bars are swaged into tungsten rods with a diameter of about 3mm, and then drawn into tungsten filaments of different thicknesses through dies. For ultra-fine tungsten filaments with a diameter of less than 12μm, electrolytic corrosion is required for precision processing. Finally, heat treatment is performed to eliminate internal stress generated during drawing and winding.
Cutting-Edge Technological Breakthroughs
In recent years, driven by the demand for high-end applications, tungsten filament manufacturing technology has achieved multiple breakthroughs. In terms of ultra-fine wire preparation, the wire diameter of tungsten filaments for photovoltaic diamond wire cutting has been reduced from 50μm in 2020 to below 38μm, and the mass production of 30μm ultra-fine tungsten filaments has been gradually realized, with tensile strength improved to 4500MPa and single wire length exceeding 300 kilometers, reducing silicon wafer cutting loss by 40%.
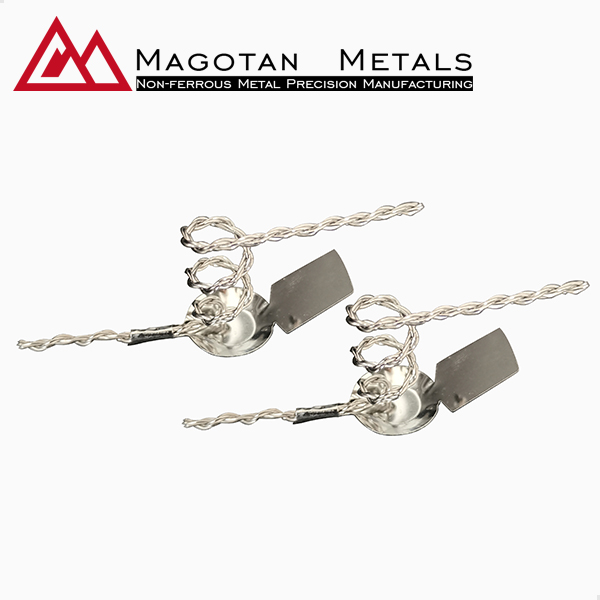
In terms of structural design, the research team of the University of Michigan has developed a spiral twisted tungsten filament. By processing 50μm diameter tungsten filaments into a spiral structure with a pitch of 100-500μm, it can spontaneously generate elliptically polarized light during thermal radiation, with a polarization degree of over 70%. This breakthrough eliminates the need for additional optical components and significantly reduces the cost of polarized light sources, opening up new applications in 3D display and biomedical detection.
In terms of intelligent and green production, the application of industrial Internet-based intelligent smelting systems has reduced energy consumption by 18% and increased product qualification rate to 99.3%. Hydrogen reduction technology is gradually replacing traditional carbon reduction technology to meet the carbon emission requirements of the EU Carbon Border Adjustment Mechanism (CBAM), and the clean energy utilization rate of new production capacity will reach more than 60% after 2025.
Application Expansion and Market Dynamics
Application Field Evolution
The application structure of tungsten filaments has undergone profound changes in recent years. The demand for traditional lighting fields has declined to 28%, while the demand for photovoltaic cutting tungsten filaments has emerged as the main driving force, accounting for 35% of the global market in 2023. With the penetration rate of N-type battery technology exceeding 50% in 2025, the demand for ultra-fine tungsten filaments in diamond wire cutting will grow exponentially, and the global market size of photovoltaic tungsten filaments is expected to reach 1.8 billion US dollars by 2030, accounting for 29% of the total tungsten filament demand.
In the semiconductor field, the popularization of 3D packaging technology has driven the demand for low-expansion coefficient tungsten filaments, with an annual growth rate of 12.4%. In aerospace and medical fields, tungsten filaments are used in high-temperature sensors, radiation therapy equipment and other components, relying on their excellent high-temperature stability and biocompatibility. In the oil and gas industry, nickel-plated tungsten filaments are widely used in downhole drilling tools and pressure gauges due to their corrosion resistance and high-temperature durability.
Global Market Pattern and Trends
The global tungsten filament market is showing a trend of steady expansion. It is predicted that the global market size will grow at a CAGR of 5.8% from 2025 to 2030, exceeding 6.2 billion US dollars by 2030. The Asia-Pacific region will contribute more than 65% of the market share, and China, as the core production and export base, will increase its capacity share from 41% in 2023 to 48% in 2030. Jiangxi and Hunan provinces in China will form industrial clusters relying on resource endowments, with a capacity share of 54% by 2025, while coastal areas will focus on high-end export products.
In terms of market competition, international leading enterprises hold technological advantages in ultra-fine tungsten filaments and composite materials, while domestic manufacturers are accelerating the replacement of high-end products through technological iteration. The industry concentration is gradually increasing, and technical barriers, patent layouts and customer stickiness have become key competitive factors. In the future, the industry will present three major trends: the proportion of high-value-added products such as rare earth-doped tungsten filaments will increase to 45%, intelligent production will further reduce costs, and the recycling rate of tungsten scrap will rise from 12% to 30%.
Challenges and Future Outlook
Industry Challenges
The tungsten filament industry is currently facing multiple challenges. In terms of cost control, the price fluctuation of tungsten concentrate is large, with a standard deviation of 18% in the past three years, which brings great pressure to production enterprises. In terms of policy constraints, the implementation of environmental protection policies such as CBAM has increased the carbon emission cost of export-oriented enterprises by 12%-15%, forcing enterprises to accelerate green transformation. In terms of technology, the localization rate of high-end products such as ultra-fine tungsten filaments for semiconductors is insufficient, and there is a risk of technological substitution by silicon carbide cutting wires.
Future Development Directions
Looking forward, the tungsten filament industry will focus on three core development directions. In terms of material innovation, research on nanocoated tungsten filaments and multi-element composite tungsten filaments will be strengthened to further improve high-temperature resistance and corrosion resistance. In terms of industrial layout, enterprises will accelerate global capacity layout, build production bases in Southeast Asia and Mexico to avoid trade barriers. In terms of circular economy, investment in tungsten scrap recycling and purification technology will be increased to realize resource recycling and reduce dependence on primary tungsten ore.
For refractory metal processing enterprises, grasping the technological iteration rhythm of the tungsten filament industry and focusing on the segmented demand of high-end fields such as photovoltaics and semiconductors will be the key to gaining competitive advantages. Through continuous R&D investment and process optimization, tungsten filaments, as a traditional refractory metal product, will continue to glow with new vitality in the wave of global manufacturing upgrading.